Mortgage costs in November 2026: what London landlords should check now
A change in Bank Rate attracts attention immediately. Its effect on a landlord’s monthly costs can arrive at a different time. The useful starting point is the mortgage agreement: the rate type, the date the current deal ends and the lender’s terms.
What changed this month?
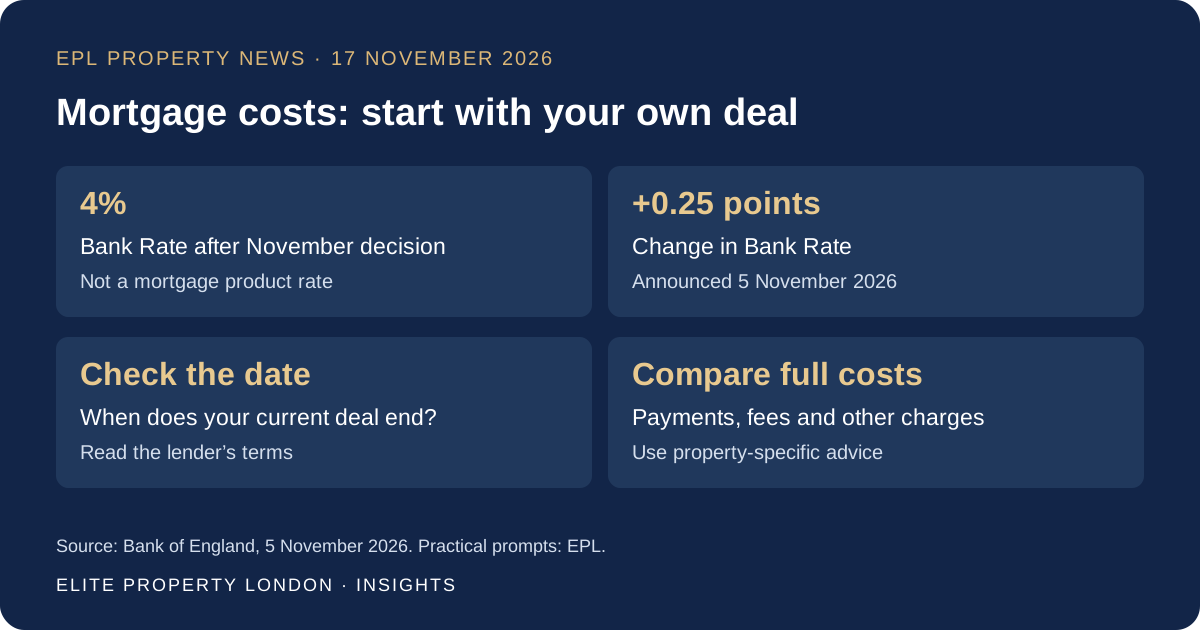
On 5 November 2026, the Bank of England announced an increase in Bank Rate from 3.75% to 4%, following an 8–1 vote. It also made clear that future policy is not on a predetermined path. The next scheduled decision is 17 December.
The 4% figure is Bank Rate, not a mortgage offer. It should not be entered into a property budget as though every lender will offer it. The price and availability of a particular mortgage depend on the product and borrower.
Start with the product you actually hold
A fixed-rate deal generally keeps its rate for the agreed period. A tracker follows its specified benchmark under the contract, while a standard variable rate is set by the lender. The timing and size of a payment change therefore depend on your terms. Check the lender’s notification rather than assuming an immediate, identical increase for every mortgage.
Put the renewal date beside the property plan
Record the current balance, rate, monthly payment and deal end date. Keep the latest lender statement with those figures. If a renewal is approaching, ask a suitably authorised mortgage adviser to compare options appropriate to the property and intended letting arrangement.
A property plan can change while the finance remains the same. Before switching to a company let or short-let use, ask the lender whether the proposed arrangement is permitted. Describe the actual use and parties clearly; a marketing label is not enough to establish consent.
Compare total costs, not just the headline rate
MoneyHelper recommends checking arrangement fees and early repayment charges when comparing deals. Its general mortgage guidance is a useful starting point; landlords need advice suited to their own borrowing and circumstances.
- Compare quotations over the same period and on the same repayment basis.
- Separate mortgage payments from insurance, service charges, maintenance and other property costs.
- Record which figures are confirmed and which remain estimates.
- Keep the rent proposal and finance assumptions dated so they can be reviewed together.
Illustrative example
Worked example: a £300,000 interest-only balance
Illustration only, not an EPL client case or mortgage quotation. Assume the mortgage rate itself rises from 5% to 5.25%, the balance stays at £300,000 and the change applies for a full year.
- Monthly interest at 5%
- £1,250
- Monthly interest at 5.25%
- £1,312.50
- Monthly difference
- +£62.50
- Annual difference
- +£750
Calculation: balance × annual rate ÷ 12. This excludes fees, capital repayments and daily-interest variations. It illustrates sensitivity to a rate change; it does not predict how a particular lender will respond to Bank Rate.
EPL’s view: timing matters as much as the headline
A rent figure on its own cannot explain whether an arrangement meets an owner’s needs. The point at which finance costs change, the work a property requires and the allocation of responsibilities all belong in the same assessment. Ask for the proposed rent, term and responsibilities in writing before comparing alternatives.
Checked on 17 November 2026. General market information, not a mortgage recommendation. Product suitability and affordability require advice based on your circumstances.